

We know the market lives in the future, and while we should gain some insights from Thursday’s Mexico CPI print (core CPI is expected to fall from 7.32% to 7.03%), it’s the Banxico meeting that will get the attention. Almost certainly leaving rates on hold at 11.25%, the debate among strategists is centred on the tone of the statement to get clarity on what month Banxico start to ease rates, as well as the pace and frequency.
Naturally, we question when we do reach the point when Banxico cuts rates and whether it leads to a key lasting reversal in USDMXN that possibly ends the multi-year bear trend or proves to be yet another bear market rally.
The path for Banxico to ease
If core CPI does indeed stay above 7%, the most probable scenario is that, like many G10 central banks, Banxico maintains a line of least regret and holds a patient stance. While obviously keen to avoid any significant economic fragility, the idea is to keep rates at restrictive levels, subsequently keeping its foot held down on the inflation-fighting peddle and aiming for core inflation to push below 5.5% by year-end.
The persistent strength in the MXN will further weigh on inflation, especially in the goods and merchandise metrics, which are already falling at a decent pace. We’ve seen Mexico's PPI inflation crater from 9.06% in July 2022 to current levels of 2.08% and that will also help reduce CPI inflation. Services inflation, however, like many developed economies, is frustratingly sticky.
As a result of the underlying economic trends, Banxico deputy Governor Heath recently suggested that we could see the bank start to cut rates by November. There are many others within the central bank who consider December a more fitting date to reduce the bank rate, but there is certainly a growing appetite to gradually take the overnight rate towards a more neutral setting.
We can look forward and see the forward interest rate markets pricing 184bp (basis points) of cuts over the coming year and 385bp of cuts over the next 2 years
While we expect the Banxico to ease at a faster pace than the Fed over any period, it is obviously coming from a different starting point, where interest rates are far higher in Mexico. This may partially explain that in the past month, USDMXN has failed to rally despite US 2-year Treasury yields gaining around 100bp relative to Mexico's 2-year bond yields – in fact, we see that USDMXN fell to the lowest levels since 2015.
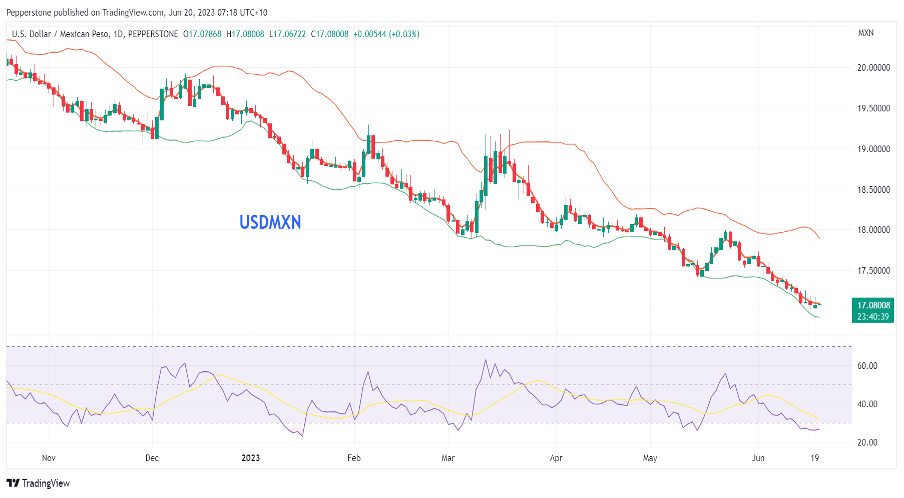
A big consideration is that the USD has found good sellers against most major currencies throughout June. Much of that can be explained by a desire to be long carry, which would explain why the MXN performed so admirably over the past month and only bettered by the ZAR and BRL.
Diminishing levels of carry for MXN buyers
We can see USDMXN 12-month forward points falling sharply of late, but they are still quite attractive at 11,509 – this is important as forward points guide to the attractiveness of a currency for its carry (or income). Changes in forward points have big implications not just for speculators but, importantly, for corporate treasury departments, who will look to hedge their exchange rate risk and lock in forward rates of foreign exchange.
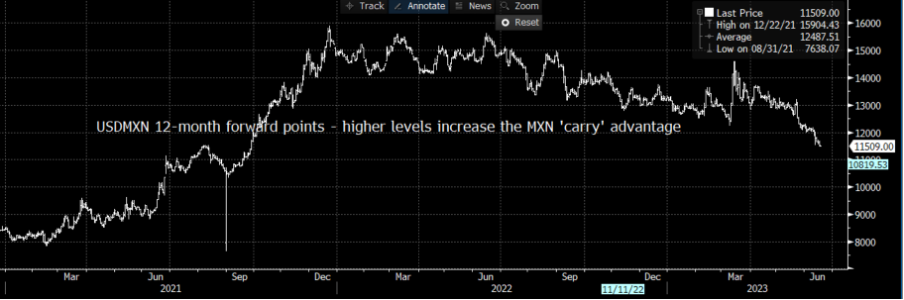
If the level of ‘carry’ is falling fast then they may hold more urgency to hedge forward exposure, which would support the MXN.
There will be a point though where that level of ‘carry’ fails to support the MXN.
We also know that many LATAM central banks started their hiking cycle before G10 central banks did. In turn, these banks are now likely to start easing policy well in advance too. Chile also is a candidate to commence an easing cycle.
In theory, as relative policy rates converge and inflation falls more intently (in Mexico) to target, we should start to see the USD outperform. Of course, relative (US vs Mexico) growth dynamics and broad financial market volatility really matter – where, should we get a market shock, the need to hold USDs as a portfolio hedge will also be a major USD driver.
Bear market rally or lasting trend change?
But from a pure interest rates perspective, the question for traders is whether any easing cycle from Banxico leads to a prolonged reversal in USDMXN, or whether it proves – yet again – to be a tradeable bear market rally that swiftly fizzles out. USDMXN has been a trend-followers dream for some time – the question is whether this time could be different.
Related articles
Pepperstone不保证这里提供的材料准确、最新或完整,因此不应依赖这些信息。这些信息,无论来自第三方与否,不应被视为推荐;或者买卖的要约;或者购买或出售任何证券、金融产品或工具的邀约;或者参与任何特定的交易策略。它不考虑读者的财务状况或投资目标。我们建议阅读此内容的任何读者寻求自己的建议。未经Pepperstone批准,不得转载或重新分发这些信息。