

As many will be aware, we’ve seen the trade-weighted JPY break to new lows, as USDJPY breaks above 143.0, with bullish breakouts playing out all over the JPY crosses. EURJPY and CHFJPY have both been well traded, with the latter breaking to levels not seen since 1979.
Conditions as good as you’ll see for FX carry
We know the conditions have been ripe for a one-way JPY move. Recently, we’ve all seen renewed concerns about frustratingly sticky core inflation, and this has led to the RBA, BoC, BoE, and Norges Bank to hike rates by more than expected - the PBoC underwhelmed by cutting its 5-year prime rate by ‘just’ 10bp. The BoJ, in comparison, remains steadfast in its uber-dovish approach, and while many debate if we see tweaks to its YCC (Yield Curve Control) program in the July BoJ meeting, for now, there is central bank policy divergence 101 playing into the JPY move.
The bond market speaks out. We can look at LATAM EM FX, where there have been some huge ‘carry’ moves in MXNJPY and COPJPY – however, it's USDJPY which is always central to the market focus.
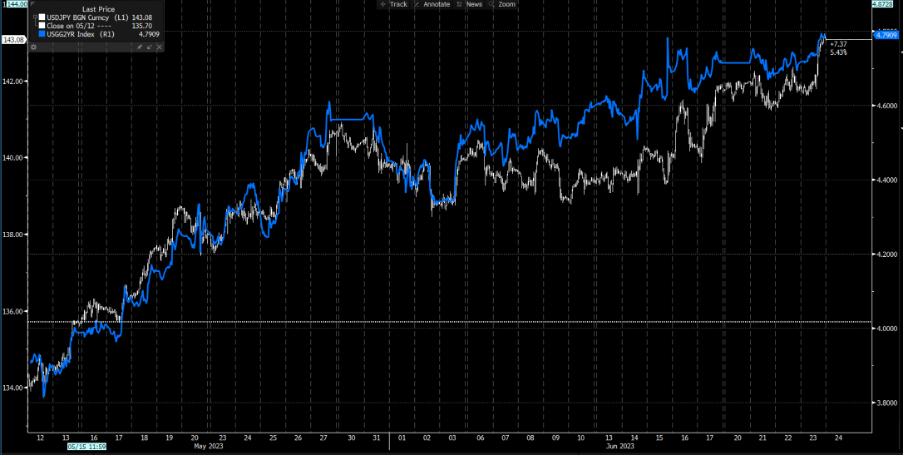
It’s the move in the US 2-year Treasury which is driving the show, where eyes fall on a potential break of the recent cycle highs of 4.79%. As US (and other global) bond yields move higher and in favour of the USD, this incentivises yield chasers, and hence with JPY having a very low JGB yield, we have seen a universal drawdown in the JPY.
If funds can capture a lasting trend in price and get paid to be in that position, it is pure gold – trend followers/CTAs would be max long this move and doing very nicely
We can see USDJPY 12-month forward points fall into new lows at -804. So, any Japanese corporate treasury department can lock in USDJPY in 12 months at lower levels (i.e. better levels if you’re long).
The cost for Japanese pension funds to hedge their USD exposure on US Treasurys investments has increased dramatically through 2022-2023 - pension funds have hedging limits they need to adhere to, but if they can refrain from selling USD (buying JPY) to hedge, they have done so.
As with any good carry position, it's not just central bank policy divergence and yield differential that is important – low volatility is essential for carry to work, and we have that in spades. USDJPY 1-Month implied volatility is now 8.59% and the lowest since April 2022. In equity land, the VIX index trades below 13%, while US bond volatility (MOVE index) has pulled back to near 12-month lows.
What’s more, US and DM equity markets remain well supported, and all carry traders love a positively trending/low vol equity market.
Is intervention coming?
This one-way JPY move would not have gone unnoticed by the BoJ and MOF (Japanese Ministry of Finance). Subsequently, the prospect that we start to see headlines of Japanese authorities ‘watching FX moves” has clearly risen, as the trend and the rate of change will not sit well with them.
There is also growing political pressure to act too, and if inflation continues to heat up – because of the JPY weakness – then the BoJ/MoF will face the music.
Verbal intervention is now a real risk, and when we hear it, the BoJ/MoF are effectively putting JPY shorts on notice that FX intervention is close at hand. Alternatively, the BoJ could tweak its YCC policy, but this seems far less likely for now.
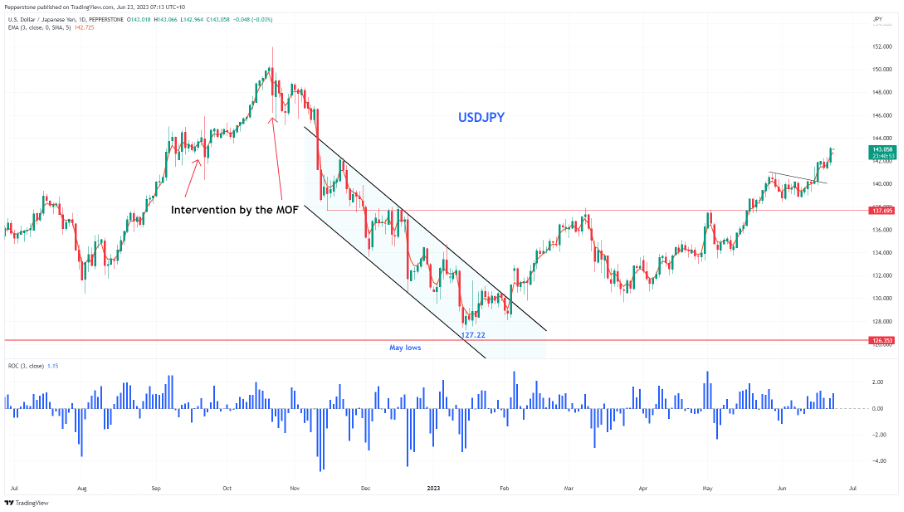
We should take intervention threats as highly credible – many will recall the 515-pip initial sell-off (in USDJPY) on 22 September and 541-pip on 21 October, as Japan bought record levels of JPY. They meant business, and while we saw funds using the weakness in USDJPY to average into new longs on 23 September, it was far more effective in October and marked the highs and what proved to be a 16% decline.
Insights for tactical traders:
- For now, the trend is undeniably powerful, and JPY shorts are all the rage – carry is king, and getting paid to make money is very compelling.
- However, if we see headlines that the Japanese authorities are watching FX, then JPY traders are firmly on notice.
- From here - JPY shorts may part cover, and we may well see liquidity dry up, which could exacerbate moves.
- If we do see FX intervention, it may come without warning and result in a 300-500 pips sell-off – how would that affect your position?
- Consider position sizing and leverage as we roll higher in the JPY pairs – a rapid decline could result in slippage, given the intensity of the move.
- I would expect the JPN225 to get hit hard – recall, foreign buyers of Nikkei stocks/futures have done so largely unhedged – so if the JPY rallies hard, the JPN225 could be down 3-4% easily.
- More aggressive traders may look for long JPY positions to capture intervention once we’re on notice. We look for price moves that indicate it's on – in September, the intervention occurred at 17:55 AEST, in October at 01:37, so they like to mix it up.
So, with the JPY-funded trade in full effect, we watch for headlines – JPY shorts may need to tread a little carefully up here.
Related articles
Pepperstone不保证这里提供的材料准确、最新或完整,因此不应依赖这些信息。这些信息,无论来自第三方与否,不应被视为推荐;或者买卖的要约;或者购买或出售任何证券、金融产品或工具的邀约;或者参与任何特定的交易策略。它不考虑读者的财务状况或投资目标。我们建议阅读此内容的任何读者寻求自己的建议。未经Pepperstone批准,不得转载或重新分发这些信息。