• 首页
  • 合作伙伴
  • 帮助和支持
Pepperstone logo
Pepperstone logo
  • 交易方式
    • 交易账户

      根据您的交易策略,选择两种账户类型之一

    • 优质客户

      专属奖励与定制化礼遇,尽享高频交易者尊贵特权

    • Pepperstone 定价

      探索我们的超低点差,以及所有其他可能费用

    • 交易时间
    • 维护
    • 入金和出金
    • 分级保证金
  • 市场
    • 外汇差价合约

      在主要货币对(如 EUR/USD)、次要货币对以及冷门货币对上享受超值报价

    • 商品差价合约

      交易金属、能源及农产品,原油点差低至 2 美分起

    • 股票差价合约

      低佣金股票差价合约

    • ETF 差价合约
    • 指数差价合约
    • 货币指数差价合约
    • 指数差价合约的股息
    • 股票差价合约的股息
    • 差价合约远期
    • 永续差价合约
  • 交易平台
    • TradingView

      通过享誉全球的超级图表进行交易,享受极具竞争力的价格

    • MetaTrader 5

      探索我们先进执行技术带来的极致自动化交易体验

    • Pepperstone 平台
    • MetaTrader 4
    • 跟单交易
    • cTrader
    • 交易工具
  • 市场分析
    • 驾驭市场

      获取专家团队带来的最新新闻与分析

    • 每日新闻

      定期掌握关键事件一览

    • 会见分析师

      我们的全球团队,为您的交易赋能

  • 学习
    • 交易指南

      交易指南与教育资料

    • 网络研讨会

      拓展你的知识

  • 关于我们
    • 会见分析师

      Pepperstone源自于让交易体验更优的愿景

    • 公司新闻
    • 公司荣誉
    • 保护在线客户
    • 交易账户

      根据您的交易策略,选择两种账户类型之一

    • 优质客户

      专属奖励与定制化礼遇,尽享高频交易者尊贵特权

    • Pepperstone 定价

      探索我们的超低点差,以及所有其他可能费用

    • 交易时间
    • 维护
    • 入金和出金
    • 分级保证金
    • 外汇差价合约

      在主要货币对(如 EUR/USD)、次要货币对以及冷门货币对上享受超值报价

    • 商品差价合约

      交易金属、能源及农产品,原油点差低至 2 美分起

    • 股票差价合约

      低佣金股票差价合约

    • ETF 差价合约
    • 指数差价合约
    • 货币指数差价合约
    • 指数差价合约的股息
    • 股票差价合约的股息
    • 差价合约远期
    • 永续差价合约
    • TradingView

      通过享誉全球的超级图表进行交易,享受极具竞争力的价格

    • MetaTrader 5

      探索我们先进执行技术带来的极致自动化交易体验

    • Pepperstone 平台
    • MetaTrader 4
    • 跟单交易
    • cTrader
    • 交易工具
    • 驾驭市场

      获取专家团队带来的最新新闻与分析

    • 每日新闻

      定期掌握关键事件一览

    • 会见分析师

      我们的全球团队,为您的交易赋能

    • 交易指南

      交易指南与教育资料

    • 网络研讨会

      拓展你的知识

    • 会见分析师

      Pepperstone源自于让交易体验更优的愿景

    • 公司新闻
    • 公司荣誉
    • 保护在线客户
Volatility

Rising Rates Set To Dent Real Estate

Michael Brown
Michael Brown
Senior Research Strategist
2023年6月22日
Share
As central banks move towards the end of what have been rapid, and sizeable tightening cycles, the full lagged effects of the interest rate hikes delivered over the prior 18 months are starting to feed through into the economy. Nowhere is this clearer than in the housing market, given the well-known sensitivity of real estate to rising rates.

There are two areas to consider when it comes to real estate – residential, and commercial. The latter remains under considerable pressure, not only from tighter monetary policy, but also as the broader macroeconomy continues to adjust to working habits in the post-covid world, with remote/hybrid working continuing to depress office occupancy rates, while also exerting pressure on city centre businesses reliant on worker traffic, such as restaurants and cafés.

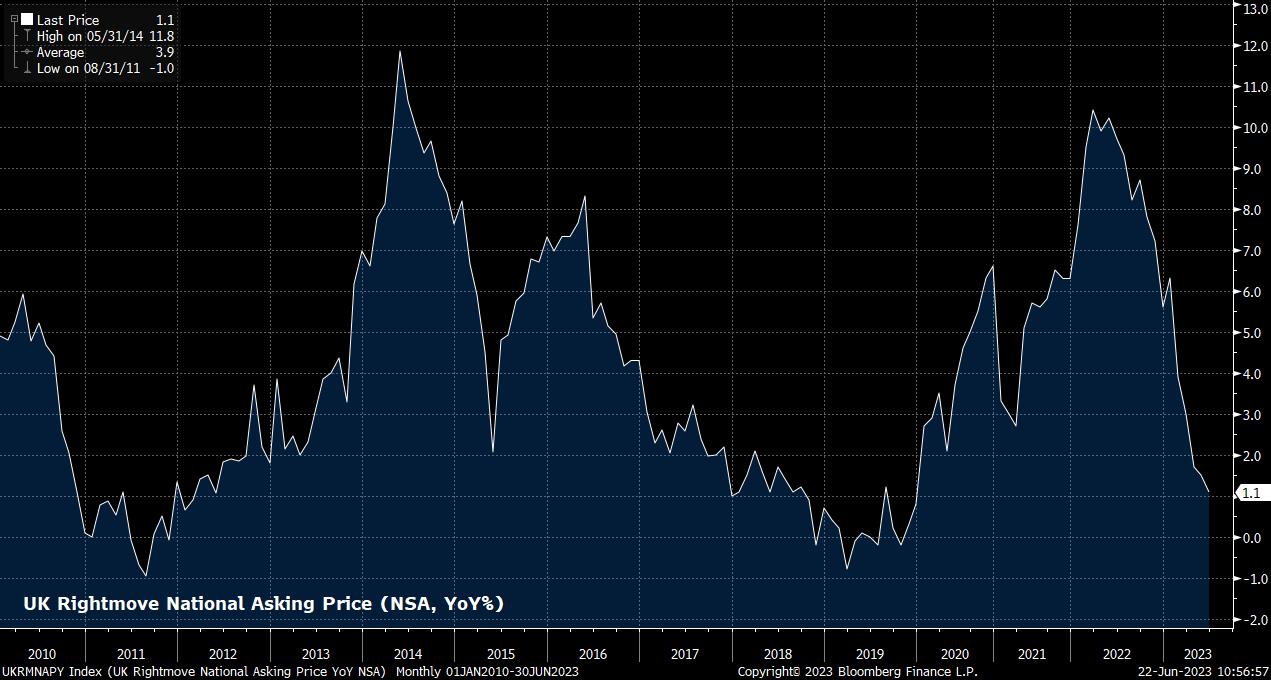
It is, however, the residential real estate market that is more likely to prove a tradeable theme, particularly in the FX space. Several G10 economies display similar characteristics, whereby house prices have rapidly increased in recent years, a mortgage cliff (where fixed rate deals are being refinanced at rates double, or more, than the original loan) is rapidly approaching, and where the risk of both substantial delinquencies and a sharp fall in house prices is high. Australia, Sweden, and the UK would be the primary economies falling into this camp.
Preview

In the case of the UK, the situation is particularly stark, and a good example of both how lagged the effects of policy tightening can be, and what may develop in other developed economies. Around 2mln fixed rate mortgages, with rates below 2.5%, will roll off between now and the end of 2024; with the current 2-year fix averaging north of 6%, many of these borrowers will see interest costs treble overnight. The rate rise itself, however, has not been overnight, with the BoE having been tightening policy since December 2021, though it is only now that the impact of said hikes is feeding through into the economy.

Perhaps more importantly, not only has the impact of tightening been delayed, it is also likely to be more prolonged, given the increasing tendency to fix mortgage rates for a longer period of time – the majority of fixed rate loans extended YTD have been for a tenor of at least 5 years. This, consequently, will mean that when the BoE eventually begin to loosen policy – at some point in the future – the impact of said cuts will not be immediately felt, thus leading to the present level of rates acting as an economic drag for some time to come.
Preview

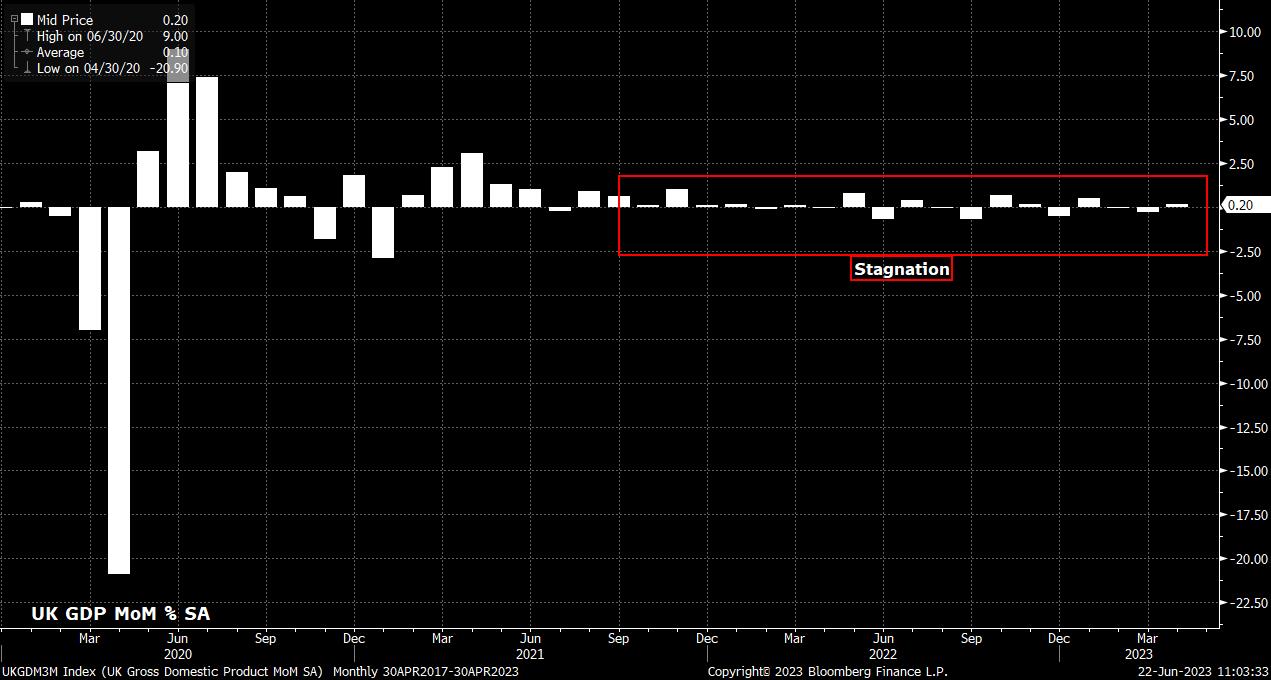
This makes a structural bull case for the GBP rather tough to come by, especially considering that the bulk of this mortgage refinancing will come later this year, leading to a significant drop in disposable income, likely denting discretionary spending, as consumers tighten their belts. While this will, hopefully, have a much-needed disinflationary impact on the economy, it will likely serve to deepen the stagnation that already plagues the UK.

Preview

A similar trend is likely to be seen in other economies, and currencies, with similar characteristics – such as the SEK and the AUD, where it is noticeable that both central banks have been almost as reluctant as the Bank of England to tighten policy, lest it have a significant detrimental impact on their respective real estate markets.

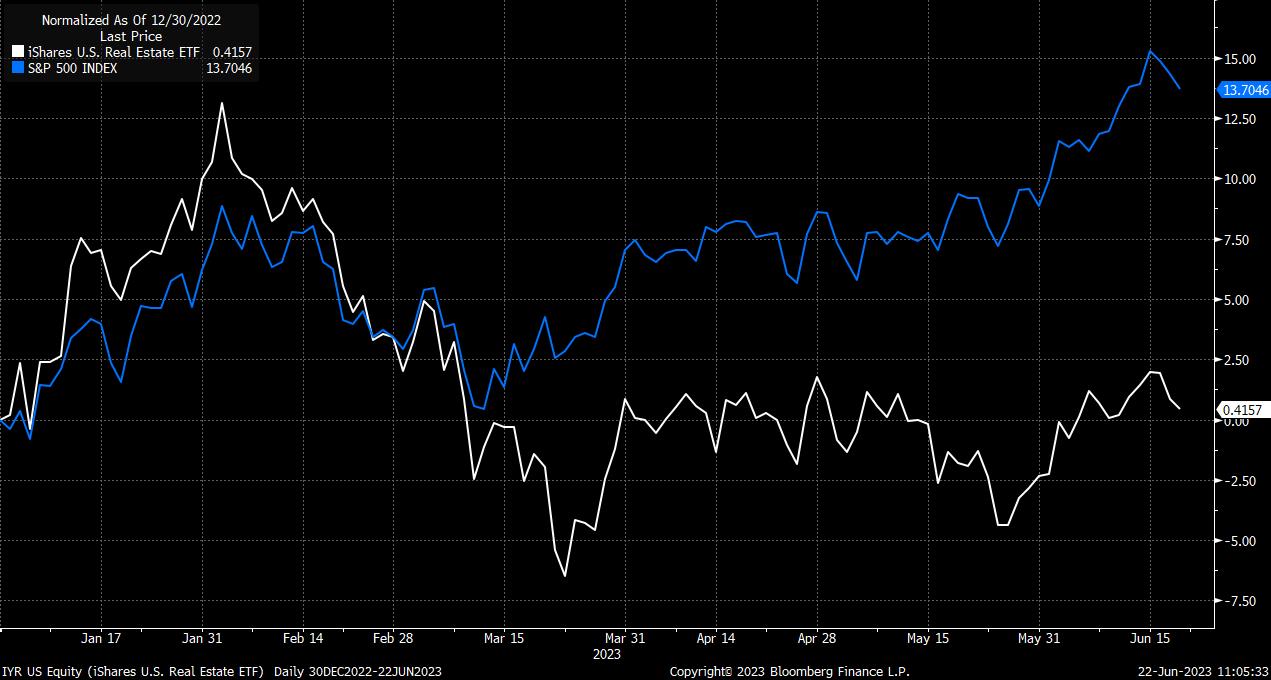
Outside of the FX space, there are other ways for traders to gain exposure to the broader real estate theme. The iShares US Real Estate ETF is one that could be considered, and a fund which exhibits broader investor angst over the state of the sector, given its considerable underperformance compared to the broader S&P 500 YTD.
Preview

Related articles

US equity playbook – new all-time highs or will falling liquidity impact?

US equity playbook – new all-time highs or will falling liquidity impact?

Volatility
Will It Be The Summer Of The Carry Trade?

Will It Be The Summer Of The Carry Trade?

Volatility
这里提供的材料并未根据旨在促进投资研究独立性的法律要求进行准备,因此被视为营销沟通。尽管不受任何关于在投资研究传播之前进行交易的禁令,我们不会在向客户提供信息之前寻求任何利益。

Pepperstone不保证这里提供的材料准确、最新或完整,因此不应依赖这些信息。这些信息,无论来自第三方与否,不应被视为推荐;或者买卖的要约;或者购买或出售任何证券、金融产品或工具的邀约;或者参与任何特定的交易策略。它不考虑读者的财务状况或投资目标。我们建议阅读此内容的任何读者寻求自己的建议。未经Pepperstone批准,不得转载或重新分发这些信息。

其他网站

  • 合作伙伴
  • 集团
  • 加入我们

交易方式

  • 定价
  • 交易账户
  • 高净值客户
  • 交易时间

平台

  • 交易平台
  • 交易工具

市场与符号

  • 外汇
  • 股票
  • 交易所交易基金
  • 指数
  • 大宗商品
  • 货币指数
  • 加密货币
  • 差价合约远期

分析

  • 市场导航
  • 每日简报
  • 会见分析师

学习交易

  • 交易指南
  • 视频
  • 在线讲座
Pepperstone logo
support.cn@pepperstone.com
C/O Credentia International Management Ltd, The Cyberati Lounge, Ground Floor, The Catalyst, Silicon Avenue, 40 Cybercity, 72201 Ebène, Republic of Mauritius.
  • 法律文件
  • 隐私政策
  • 网站条款与条件
  • Cookie政策

风险警告:差价合约是复杂的工具,由于杠杆作用,存在着迅速亏损的高风险。您应该考虑是否了解价差合约的运作方式,以及您是否有能力承担损失资金的高风险。您不拥有标的资产的所有权或权利。过去的表现并不代表未来的表现,并且税法可能会发生变化。本网站上的信息是一般性信息,并未考虑您或您客户的个人目标、财务状况或需求。请在制定任何交易决定之前,阅读我们的《风险披露通知》和其他法律文件。我们鼓励您寻求独立的建议。


Pepperstone Financial Markets Limited 位于 C/O Credentia International Management Ltd, The Cyberati Lounge, Ground Floor, The Catalyst, Silicon Avenue, 40 Cybercity, 72201 Ebene, Republic of Mauritius。 获得毛里求斯金融服务委员会颁发的牌照和并接受其监管。 (牌照号码:GB21026314)  


本网站上的信息和提供的产品和服务并非要推销给任何国家或司法管辖区的任何人,如果此类推销或使用违反当地法律或法规。


©2026 Pepperstone Financial Markets Limited | 公司注册号180497 GBC。