

The prospect of the Fed hiking in June will get further close attention, where we contrast how US data stacks up relative to the data flow in other economic heavyweights.
We look at the strong repricing of the number of cuts in the US by year-end 2023, which now stand at just 8bp (we were recently pricing 80bp of cuts this year) and we watch the US exceptionalism story, with Chinese economic data and equity performance getting huge interest.
The USD rallied for five consecutive days last week, partly driven by US 2yr Treasuries, which gained 29bp on the week - taking the tally of consecutive gains (in yield) to 11 days. Only the MXN stood tall vs the USD, while the NZD, SEK and AUD lost between 2% and 3.7%. USDCNH remains central to the broad USD flows, and as the USD gains vs the yuan, we see the USD stage a broad rally vs G10 FX – USD shorts will want this cross to head lower this week.
(HK50 daily)
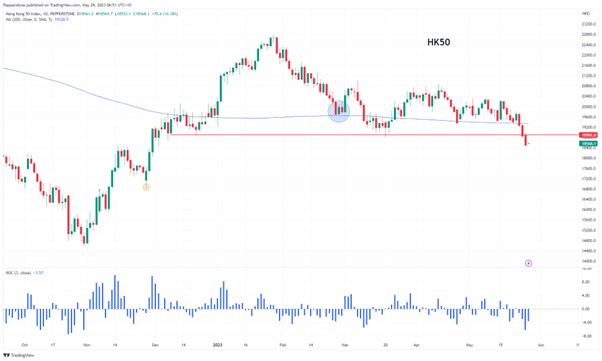
We see bearish range breaks in the HK50 and CHINAH, and we ask whether price action can really start to trend lower. This bearish flow has partly been a Chinese data story, but the strong USD and higher yields on offer is causing capital to exit these markets. The USD is central to the price action this week, but do we chase this lower or is the risk the authorities step in front of this weakness?
While China has been a source of concern – and a solid trading opportunity – the AI thematic kicks further. There is a lot of love in this space now and its red hot, but is it too hot? The NAS100 is a momentum powerhouse, and one questions if we can see the Feb/March 2022 highs (at 15,265) come into play in the next few weeks. It’s hard to bet against mega-cap tech/AI plays/semi’s but they are the market. The NAS100 is an incredible chart though and helping my long NAS100 / short EUSTX50 trade nicely.
Anyhow as the flow of information shifts, its good to see some movement, range breaks and some momentum kick into our core markets.
Marquee data points for the week ahead
US nonfarm payrolls
(Friday 22:30 AEST) – the NFP report is the marquee event risk of the week, where the outcome could influence the pause/hike debate for the June FOMC. The market eyes 190k net jobs created, with the economist’s range of estimates set between 235k and 100k. The unemployment rate is eyed at 3.5% (from 3.4%), with Average Hourly Earnings (AHE) at 4.4% YoY/0.3% MoM.
The form guide suggests a higher probability that we see a hot payrolls, with the last 13 reports printing above consensus. I think the market knows this only too well and will likely be positioned for 220k-250k. If the U/E comes in at 3.4% I think the market increases the prospect of a June Fed hike closer to 60-70%, which should lift the USD.
EU CPI
(Thurs 19:00 AEST) – The market expects the headline CPI estimate at 6.3%, which would be a fair drop from the prior print of 7%, although this is largely driven by energy-related base effects. Core CPI is eyed at 5.5% (from 5.6%) – a hike in the June ECB meeting is fully priced, but the barrier to a 50bp increment is high – we look further out the rates ‘curve’, where we could see expectations of hikes in future months being priced in/out. EUR longs look best vs SEK and JPY at this juncture, while EURUSD will also be looking closely at China’s data this week and how USDCNH reacts.
US ISM Manufacturing
(Friday 00:00 AEST) – the market looks for the diffusion index to come in at 47.0 (from 47.1). A reading above 50 (above 50 shows expansion, below is contraction) would shock markets and promote USD buyers, with further selling (higher yields) in US 2yr Treasuries. The market has seen this data point below 50 since November, so it would not be shocked by another month-on-month contraction. The bigger market’s reaction likely comes on a hotter print, although the sub-components of the report– new orders and prices paid – could also be influential.
US JOLTS job openings
(Thurs 00:00 AEST) – while the NFP report is the more influential labour market read, the market expects a further decline in job openings with the consensus at 9.439m (from 9.59m). The jobs openings report is losing its influence on market pricing but with the labour market still a reason for the Fed to maintain a hawkish outlook, the outcome could influence market pricing for the June Fed meeting, but we’d need to see a big miss/beat.
China manufacturing and services PMI
(Wed 11:45 AEST) – the market has seen Chinese data coming in consistently below expectations of late and that has had a big impact on global markets – the USD has benefited greatly vs G10 FX, with USDCNH marching higher. The market expects manufacturing to print at 49.5 (from 49.2) and services at 55.0 (56.4) on the diffusion index – a read above 50.0 in the manufacturing print could be a relief and see some covering of short China market (and proxies). This is a data point not just for HK50, CN50 and CHINAH traders, but also for those who trade copper, EUR, and AUD too.
Australia April (monthly) CPI
the market sees the April headline CPI print at 6.4% (from 6.3%). With Aussie rates pricing 6bp of hikes in the June RBA meeting (a 25% chance of a hike), a number above 6.6% could see that pricing closer to 10bp with the market sensing a hike could be very much on the table. Scope for AUDJPY to push into 92.70, with AUDNZD also seeing good upside momentum.
Holiday trading hours (both Monday) - Memorial Day (US) and Spring Bank Holiday (UK)
Central bank speakers:
Fed speakers – Barkin, Collins, Harker, Jefferson
BoE speakers – Catherine Mann (Wed 23:15 AEST) – one for the GBP traders
RBA – Gov Lowe (Wed 09:00 AEST)
ECB speakers – De Cos, Holzmann, Villeroy, Visco, Knot, ECB President Lagarde (Friday 19:30 AEST)
Stock of the week: NVIDIA
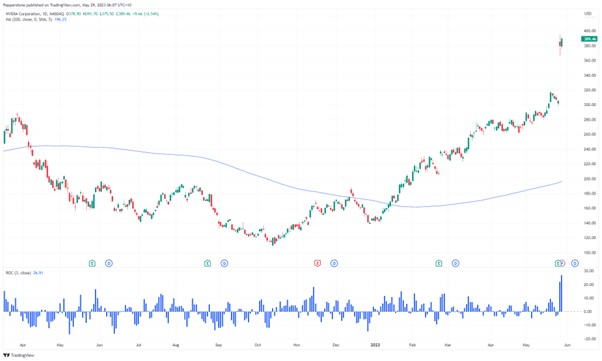
NVIDIA
while Nvidia was the stock of the week last week, it's hard to not re-focus on this name. Aside from rallying 24.6% on the week and adding $188b in market cap (now sits at $961b), the earnings and guidance absolutely blow the lights out. We simply haven’t seen a company guiding to quarterly revenue 50% above the street’s consensus, with its data centres almost doubling. Gross margin guidance of 70% shows just how far they are from the competition and why they are the industry standard. They have incredible pricing power and while competition will only intensify, it has some catching up to do. There is so much love for this name right now, but rightly so, fundamentally this is a business that is doing everything right - the question is whether Nvidia can keep kicking higher or if we see a slight reversion to the mean.
My bias is this will be a $400 stock soon, but it’s hard to chase and initiate new longs here. The fate of the NAS100 seems driven by tech and Nvidia is at the heart of that.
Broadcom, Microsoft, Meta, and AMD also feature, with shares seeing incredible strength and trending conditions.
Related articles
Pepperstone不保证这里提供的材料准确、最新或完整,因此不应依赖这些信息。这些信息,无论来自第三方与否,不应被视为推荐;或者买卖的要约;或者购买或出售任何证券、金融产品或工具的邀约;或者参与任何特定的交易策略。它不考虑读者的财务状况或投资目标。我们建议阅读此内容的任何读者寻求自己的建议。未经Pepperstone批准,不得转载或重新分发这些信息。