• Home
  • Pro
  • Partners
  • Help and support
  • English
  • Italiano
  • Español
  • Français
Pepperstone logo
Pepperstone logo
  • Ways to trade
    • CFD trading

      Trade price movements with competitive spreads

    • 24-hour trading

      Trade CFDs on key US shares 24/5.

    • Pricing

      Discover our tight spreads, plus all other possible fees

    • Trading accounts
    • Demo trading
    • Maintenance schedule
    • Trading hours
    • Risk management
    • Funding and withdrawals
  • Markets
    • Commodities

      Trade on metals, energies & softs, with oil spreads from 2 cents

    • Indices

      Take a position on whole sectors and economies, with 24/5 pricing on majors

    • Forex

      Get great rates on majors like EUR/USD, plus minors and exotics

    • Cryptocurrencies

      Speculate on Bitcoin, Ether and more, with a trusted broker

    • Shares
    • ETF
    • Currency indices
    • Dividends for index CFDs
    • Dividends for share CFDs
    • CFD forwards
    • Real World Assets (RWA)
    • Perpetual CFDs
  • Trading platforms
    • TradingView

      Trade through supercharts with tight spreads

    • MetaTrader 5

      Explore the apex in trading automation with our execution tech

    • The Pepperstone platform
    • MetaTrader 4
    • cTrader
    • Trading tools
  • Learn
    • Trading guides

      Trading guides & educational materials

    • Webinars

      Grow your knowledge

  • About us
    • Who we are

      Pepperstone was born from the dream of making trading better

    • Pepperstone reviews
    • Press releases
    • Company awards
    • Protecting clients online
    • CFD trading

      Trade price movements with competitive spreads

    • 24-hour trading

      Trade CFDs on key US shares 24/5.

    • Pricing

      Discover our tight spreads, plus all other possible fees

    • Trading accounts
    • Demo trading
    • Maintenance schedule
    • Trading hours
    • Risk management
    • Funding and withdrawals
    • Commodities

      Trade on metals, energies & softs, with oil spreads from 2 cents

    • Indices

      Take a position on whole sectors and economies, with 24/5 pricing on majors

    • Forex

      Get great rates on majors like EUR/USD, plus minors and exotics

    • Cryptocurrencies

      Speculate on Bitcoin, Ether and more, with a trusted broker

    • Shares
    • ETF
    • Currency indices
    • Dividends for index CFDs
    • Dividends for share CFDs
    • CFD forwards
    • Real World Assets (RWA)
    • Perpetual CFDs
    • TradingView

      Trade through supercharts with tight spreads

    • MetaTrader 5

      Explore the apex in trading automation with our execution tech

    • The Pepperstone platform
    • MetaTrader 4
    • cTrader
    • Trading tools
    • Trading guides

      Trading guides & educational materials

    • Webinars

      Grow your knowledge

    • Who we are

      Pepperstone was born from the dream of making trading better

    • Pepperstone reviews
    • Press releases
    • Company awards
    • Protecting clients online
  • English
  • Italiano
  • Español
  • Français
Netflix
Share CFDs
Equities

Netflix Q3 Earnings Preview: Can Ad Growth Take the Baton and Fuel the Next Leg Higher?

Dilin Wu
Dilin Wu
Research Strategist
Oct 16, 2026
Share
With subscription growth slowing, Netflix’s Q3 results will put its ability to double ad revenue, sustain user engagement and continue improving margins under the spotlight. The focus is not just on quarterly results, but on whether advertising can support the company’s next phase of growth.
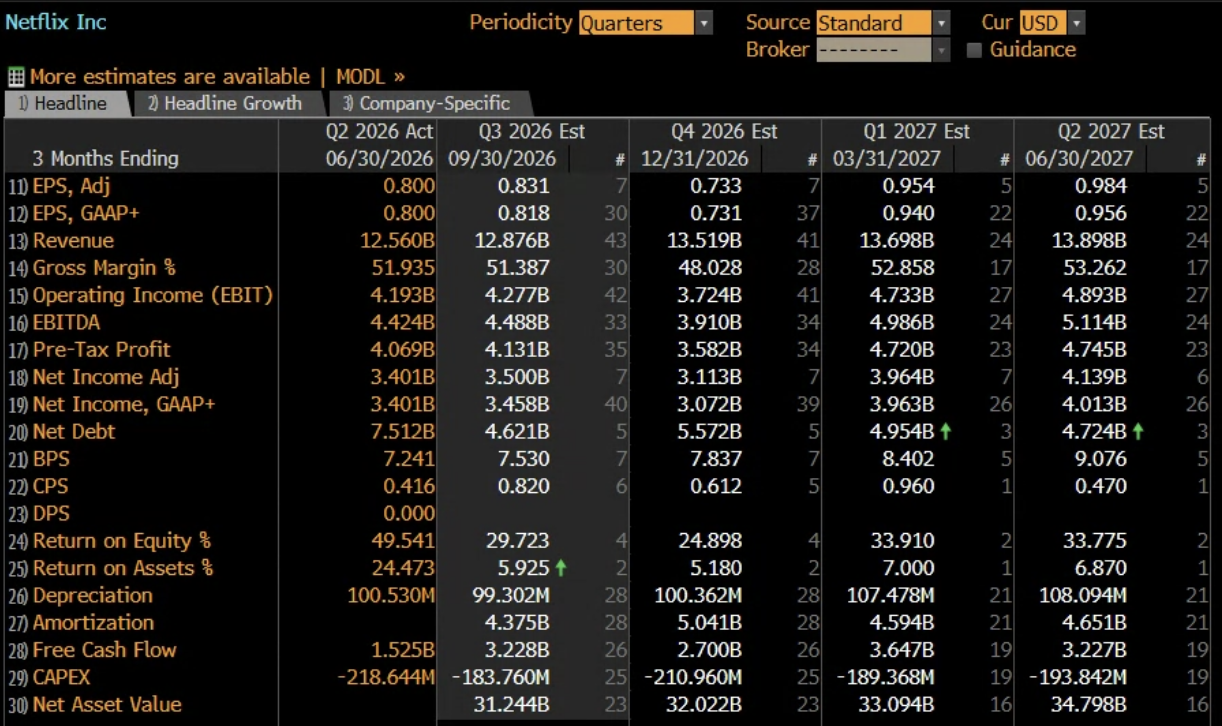
Netflix (NFLX) will report its Q3 2026 results after the US market closes on October 20. The market expects revenue of $12.876 billion, up approximately 11.9% year on year, and adjusted earnings per share (EPS) of $0.831. Notably, the Q3 guidance issued by management in July was already below Wall Street expectations at the time. This means the bar for the company’s quarterly results has been lowered.
Screenshot_2026-10-16_at_12.33.46_PM.png


Although Netflix continues to grow, the market needs to determine whether this slowdown is a natural consequence of a maturing business or a sign that content appeal and user engagement are beginning to weigh on the quality of growth.


Traders will also be watching whether advertising monetisation can unlock new growth opportunities as subscription growth gradually slows, and whether revenue gains can continue to translate into profits.

A strong track record of beating expectations, but a more sensitive market reaction

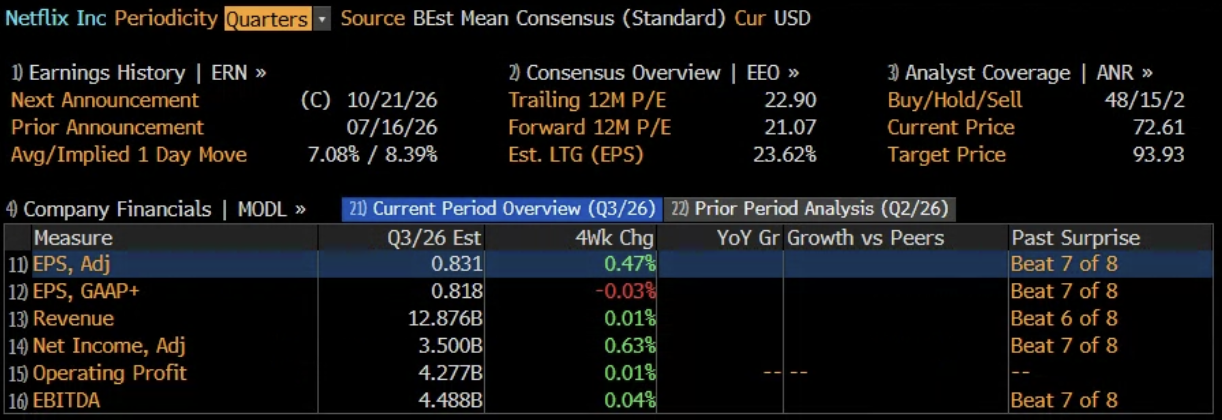
Over the past eight quarters, Netflix has beaten expectations on EPS and EBITDA seven times each, and revenue expectations six times, giving the company a solid track record of delivering results.


Analysts are also broadly optimistic. At the time of writing, of the 65 analysts covering Netflix, 48 have a “Buy” rating, 15 have a “Hold” rating and just two have a “Sell” rating. The average price target stands at $93.93, implying around 29% upside from the current share price of $72.61.
 

Screenshot_2026-10-16_at_12.32.59_PM.png


However, a history of earnings beats does not guarantee that this report will drive the share price higher. The options market currently implies a one-day move of 8.39% following the earnings release, above the historical average. This suggests the market is pricing in a sizeable share price swing. The post-earnings reaction will still depend on how actual results compare with expectations and what management signals about future growth.


Another factor worth watching is the year-on-year comparison base. The same period last year was affected by a one-off expense related to a Brazilian tax dispute, and the market expects EPS to grow by more than 37% year on year this quarter. Investors should therefore look beyond headline earnings growth and assess revenue growth, operating margins and forward guidance to determine whether underlying business momentum is genuinely improving.

Three key variables: Ad monetisation, user engagement and margins

There are three key questions to watch in Netflix’s upcoming results.


First, can advertising revenue deliver on the “doubling” guidance?


Advertising is one of the most important pillars of Netflix’s next phase of growth. Management previously forecast that ad revenue would double year on year to around $3 billion this year.


Although ad revenue growth came close to 80% in Q2, it still fell short of market expectations. Whether the advertising business can continue to deliver on its growth target and make a meaningful contribution to overall profitability will be a key test in this report.


Second, is user engagement showing any material deterioration?


Netflix is competing not only with other streaming platforms, but also with content services such as YouTube that are vying for users’ screen time. Changes in viewing hours do not necessarily mean users are leaving. The key question is whether they are beginning to affect subscription renewals, pricing power and the effectiveness of ad monetisation.


Third, can workforce reductions and changes to the cost structure translate into margin improvement?


The company recently announced around 1,000 job cuts and is shifting resources towards live sports, including World Cup broadcasting rights, and advertising.


If margins hold around 33% or improve further this quarter, it would suggest that cost efficiencies are helping offset rising content costs. Conversely, if restructuring expenses come in higher than expected or guidance weakens, confidence in a profit growth strategy driven by cost control could falter.

Technical outlook: $67 is a key downside level to watch

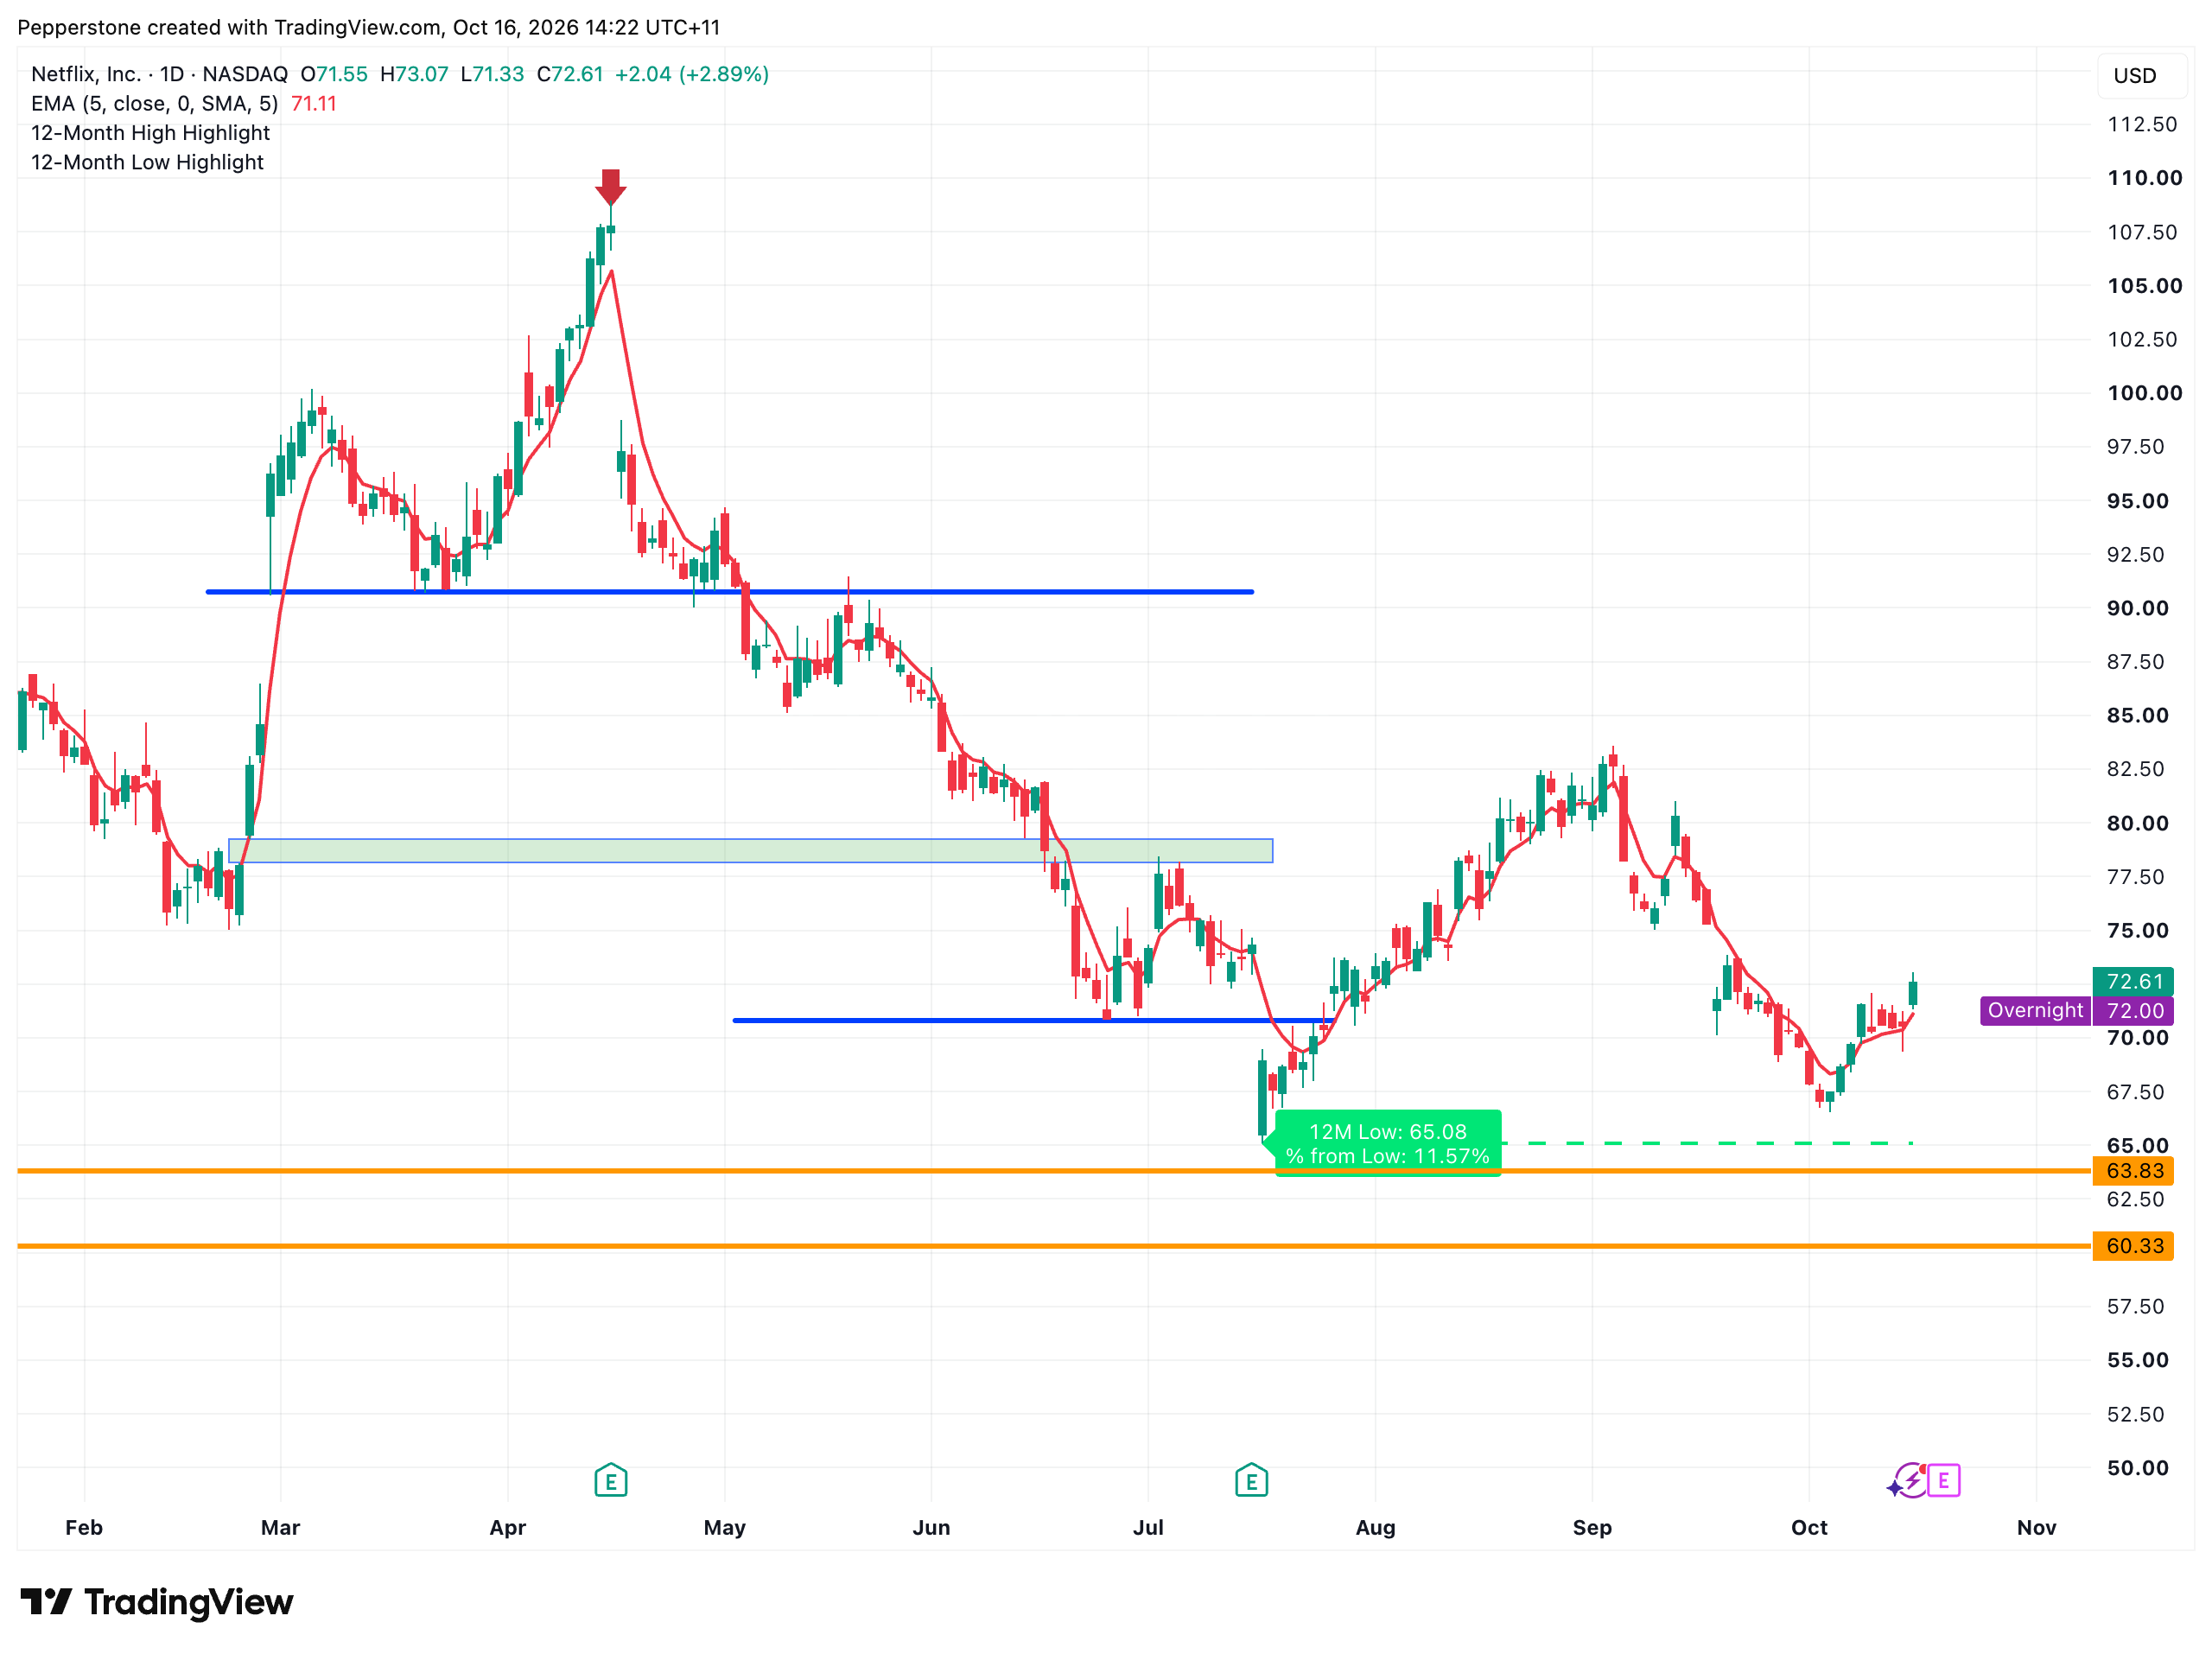
On the daily chart, Netflix shares have rebounded since early October and are currently trading around $72, but remain well below the year-to-date high of $108.95.
NFLX_2026-10-16_14-22-35.png

The early-October low near $67 is a key support level. If the share price decisively breaks below this level after the earnings release, the downside could open up towards $65 or even $60.


Conversely, if the results validate improvements in ad growth and margins, the share price could recover further towards the analyst target-price range.

Meeting expectations is only the starting point

At its core, this earnings report needs to answer one question: as Netflix’s subscription growth story slows, can advertising monetisation and cost discipline take the baton and become the company’s next growth engine?


Analyst ratings already reflect a fair degree of optimism, but the share price’s decline of more than 20% year to date, alongside persistent questions about user engagement, suggests there is limited room for disappointment.


The $67 level is an important point to watch when assessing the market’s reaction to the results. Ultimately, whether Netflix can embark on another sustained rebound will depend on whether its three key drivers — advertising, content and margins — deliver convincing results.

The material provided here has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. Whilst it is not subject to any prohibition on dealing ahead of the dissemination of investment research we will not seek to take any advantage before providing it to our clients.

Pepperstone doesn’t represent that the material provided here is accurate, current or complete, and therefore shouldn’t be relied upon as such. The information, whether from a third party or not, isn’t to be considered as a recommendation; or an offer to buy or sell; or the solicitation of an offer to buy or sell any security, financial product or instrument; or to participate in any particular trading strategy. It does not take into account readers’ financial situation or investment objectives. We advise any readers of this content to seek their own advice. Without the approval of Pepperstone, reproduction or redistribution of this information isn’t permitted.

Other Sites

  • The Trade Off
  • Partners
  • Group
  • Careers

Ways to Trade

  • Pricing
  • Trading accounts
  • Pro
  • Trading hours

Platforms

  • Trading platforms
  • TradingView
  • MT5
  • MT4
  • cTrader
  • Trading tools

Markets and Symbols

  • Forex
  • Shares
  • ETFs
  • Indices
  • Commodities
  • Currency indices
  • Cryptocurrencies
  • CFD forwards

Insights

  • Trading guides
  • Videos
  • Webinars
  • Meet the analysts

About

  • Press releases
  • Vulnerability disclosure
Pepperstone logo
support@pepperstone.com
0035725030573
195, Makarios III Avenue, Neocleous House,
3030, Limassol Cyprus
    • Legal documents
    • Privacy policy
    • Website terms and conditions
    • Cookie policy
    • Sitemap
    • Vulnerability

    © 2025 Pepperstone EU Limited
    Company Number ΗΕ 398429 | Cyprus Securities and Exchange Commission Licence Number 388/20

    Risk warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage.  74.1% of retail investor accounts lose money when trading CFDs with this provider. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.

    Trading derivatives is risky. It isn't suitable for everyone and, in the case of Professional clients, you could lose substantially more than your initial investment. You don't own or have rights in the underlying assets. Past performance is no indication of future performance and tax laws are subject to change. The information on this website is general in nature and doesn't take into account your or your client's personal objectives, financial circumstances, or needs. Please read our legal documents and ensure you fully understand the risks before you make any trading decisions. We encourage you to seek independent advice.

    Pepperstone EU Limited is a limited company registered in Cyprus under Company Number ΗΕ 398429 and is authorised and regulated by the Cyprus Securities and Exchange Commission (Licence Number 388/20). Registered office: 195, Makarios III Avenue, Neocleous House, 3030, Limassol Cyprus.

    The information on this site is not intended for residents of Belgium, Spain or the United States, or use by any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation.